Why Lottery Tickets Are Not Irrational Even When the Mathematics Clearly Say They Should Be
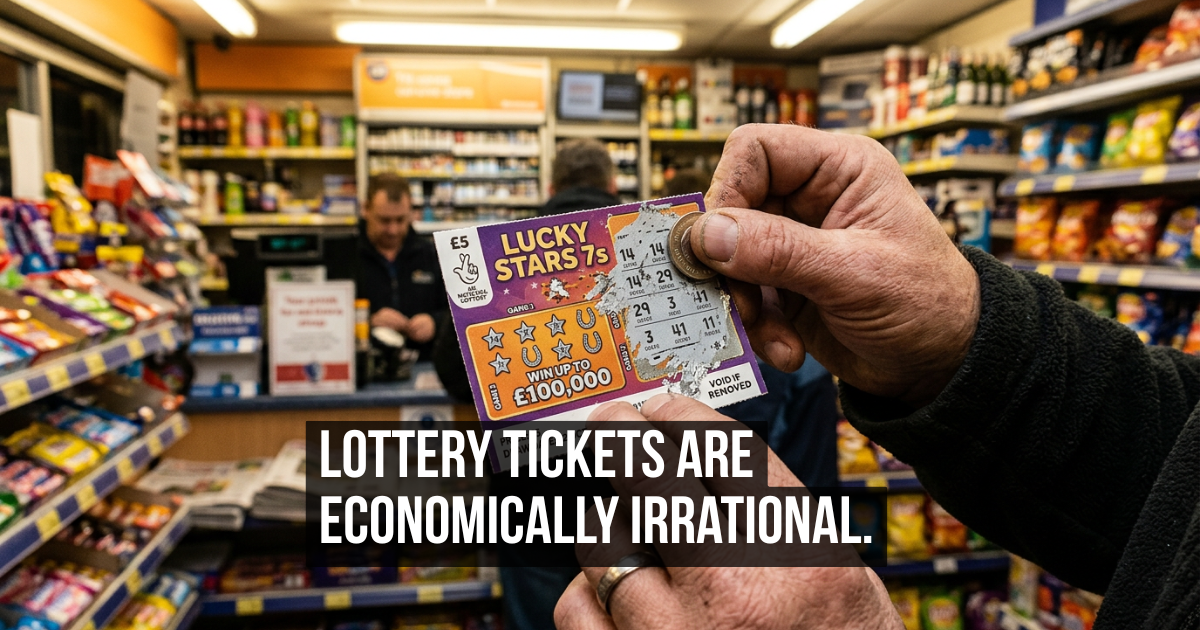
Buying a lottery ticket is routinely cited as a textbook example of irrational behavior. The expected value calculation is simple and brutal: a ticket with a one-in-fourteen-million chance of winning a jackpot worth fourteen million dollars has an expected monetary value of approximately one dollar, which is usually less than the ticket costs, and this is before accounting for taxation and lump-sum discounts that further reduce the real payout. Economists teach it as a demonstration of probability blindness. Behavioral scientists cite it as evidence of the brain’s inability to intuitively grasp the difference between very small probabilities and zero.
The argument is correct and almost entirely misses what people are actually purchasing when they buy a lottery ticket.
The Product Is Not the Jackpot
The lottery ticket’s genuine product is not the expected value of the potential payout. It is the mental experience of imagining winning — the specific cognitive and emotional state produced by holding a ticket and not yet knowing the outcome. Research on anticipation and reward consistently finds that the pleasure of anticipating a positive outcome is, in many cases, more intense and more sustained than the pleasure of the outcome itself. The ticket grants access to this anticipatory state for the duration between purchase and draw.
For the price of a coffee, the lottery provides an afternoon or an evening in which the question “what if” is not hypothetical but technically, if vanishingly, possible. The calculation of how to spend the hypothetical winnings, the imagined conversation about quitting a job or buying a house or giving money to people who need it: these are pleasurable cognitive activities that the ticket has licensed. The pleasure is real. The probability of its underlying premise is essentially irrelevant to the experience it generates.
The Utility of the Very Small Chance
Standard expected-value analysis treats a one-in-fourteen-million probability and a zero probability as functionally identical. Psychologically, they are not. Zero closes a possibility permanently. A one-in-fourteen-million chance, however vanishingly small, keeps it technically open. For people in economically constrained circumstances — whose realistic pathways to a significantly different life are limited and well understood — the lottery ticket represents the only available mechanism for introducing genuine structural uncertainty into an otherwise predictable economic trajectory.
This is not irrational in the technical sense. It is a rational response to a constrained opportunity set. The person who has no realistic investment pathway to wealth accumulation, whose income barely covers expenses, and who would not miss the price of a ticket has no expected-value alternative to compare the lottery against. The comparison economists make — lottery vs. index fund — assumes a disposable income that is being either spent on tickets or invested. For most regular lottery players, the actual comparison is ticket vs. an equivalent small expenditure on some other form of modest pleasure.
The Regressive Tax Framing
State lotteries are frequently described as regressive taxes — revenue mechanisms that extract a disproportionate share of income from lower-income households. The description is accurate in aggregate: lottery participation rates are higher in lower-income demographics, and the percentage of income spent on tickets is higher in lower-income households than in higher-income ones.
The framing is also incomplete in a specific way. It describes the lottery as a tax by comparing the money spent to the money returned in prizes and subtracting the difference. This comparison works for a product whose value is purely its monetary payout. It does not work for a product that also delivers a measurable experiential good — the anticipatory pleasure, the brief structural uncertainty, the cognitive exercise of imagining a different life. Whether this experiential good is worth the ticket price is a question the individual buyer is better positioned to answer than the economist who constructs the expected-value model.
What the Critique Gets Right
The behavioral critique of lottery participation is not wrong about the probability mathematics or the aggregate economic outcomes. It is wrong to treat the ticket as a purely financial product and its buyer as someone who has performed the expected-value calculation and arrived at an incorrect conclusion. Most regular lottery players have not miscalculated the odds. They know the odds are not in their favor. They are buying something other than a high-probability income stream, and they know it.
The contempt that attaches to lottery participation in educated discourse is, in part, the contempt of people for whom other forms of pleasurable anticipation and structural aspiration — career advancement, investment returns, professional recognition — are available as alternatives. The lottery serves a function for people for whom those alternatives are less accessible. Calling the function irrational requires ignoring what the function actually is.
Something went wrong. Please refresh the page and/or try again.
Help us improve your journey
We use cookies to personalize your experience and understand how you use our site. By clicking 'Yes, I'm in!', you help us show you content you'll actually love. If you prefer to keep things simple, you can stick to the essentials. You can change your mind anytime!
Necessary
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Analytics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Advertising
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.



Leave a Reply